
Jerry: Insurance & Car Care
- Rating
- 4.4
- Downloads
- 1.00M
- Content Rating
- Everyone
Jerry: Insurance & Car Care - Screenshots
Pros
- Combines insurance management and car-care tools in one app.
- Lets you view policy details and coverage information on the go.
- Can help track vehicle maintenance and service history.
- Useful reminders may reduce the chance of missing routine car care.
- Digital access can make roadside and support requests more convenient.
Cons
- Availability and features may vary by state
- insurer
- or vehicle type.
- Some services may require an eligible Jerry insurance policy.
- Insurance quotes require personal and vehicle information.
- Savings estimates may not match the final price you are offered.
- The app may rely on location and notification permissions for full functionality.
Jerry: Insurance & Car Care - Description
- App Name
- Jerry: Insurance & Car Care
- Package Name
- com.jerrym
- Developer
- Jerry, Inc.
- Category
- Finance
- Last Updated
- Oct 25, 2017
- Version
- 3.134.1
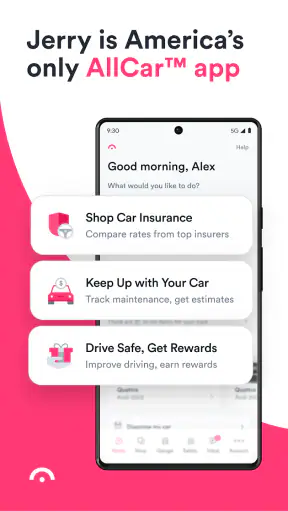
Choosing a car insurance app is not only about finding the lowest quoted number. I look for something that helps me compare coverage without losing track of what I am buying, and I also want useful support after the policy is active. Jerry: Insurance & Car Care takes a broader approach. It is a free finance app from Jerry, Inc. that brings insurance comparison, car-care costs, and safe-driving discounts into the same experience.
That combination makes it more interesting than a basic insurer app, but it also means the right question is not simply whether it is “good.” The better question is whether I want one place to explore insurance and ownership costs, or whether I would rather deal directly with an insurer, an independent agent, or a dedicated maintenance tool. After spending time with the app, I see it as a practical starting point for drivers who want to organize a decision, especially when a renewal is approaching or a vehicle is becoming expensive to keep.
What I would check before relying on Jerry
My first decision criterion is clarity. An insurance comparison is only useful when I can understand the coverage behind the quote. A lower premium can be misleading if the deductible, liability limits, optional protection, or exclusions are different from my current policy. I would use Jerry to create a shortlist, then read the policy details carefully before switching. The app can make comparison easier, but it cannot remove the responsibility of choosing suitable coverage.
The second criterion is timing. I would not wait until the last minute before a policy expires. Comparing early gives me time to check whether the apparent saving comes from changing coverage, whether the new insurer accepts the vehicle and driver details, and whether cancellation or payment arrangements need attention. Jerry is most useful when I treat it as a decision workspace rather than a button I press once to chase a cheap offer.
The third criterion is the rest of the ownership budget. Insurance is often the most visible recurring cost, while repairs, tires, servicing, registration, fuel, and unexpected faults can quietly cause more stress. Jerry’s focus on car insurance and maintenance costs is valuable because it encourages me to look beyond the monthly premium. A policy that saves money but leaves me unable to handle ordinary ownership expenses is not automatically the best choice.
I would also consider how comfortable I am sharing personal and vehicle information with a finance app. Accurate comparisons require accurate details, and drivers should review every screen before submitting information. I prefer to keep my current declarations, renewal documents, vehicle identification details, and claims history nearby so I can answer consistently. A rushed or incomplete application can make any comparison less useful.
How I would use it before a renewal
My practical workflow would begin with my current policy. I would write down the protections I already have, not just the amount I pay. Then I would use Jerry to explore alternatives and compare the result against that baseline. This matters because an unfamiliar quote can look attractive simply because it omits something I consider essential.
Next, I would separate genuine savings from temporary convenience. If a quote appears lower, I would check the deductible and limits first. I would also think about how much cash I could realistically produce after an accident. A larger deductible may reduce the regular cost, but it shifts more risk to me at the moment when I am already dealing with a claim.
Finally, I would save the details of the option I am considering and revisit them before making a change. This is one of the less obvious advantages of using a comparison-focused app: it can slow me down just enough to make the decision deliberate. I would not cancel an existing policy until the replacement is confirmed and the dates line up.
Where Jerry feels stronger than the usual insurance app
Most insurer apps are designed around an existing customer relationship. They are excellent for viewing a policy, paying a bill, requesting help, or managing a claim with that company. Jerry approaches the problem from the other direction: it is useful when I am still deciding where my insurance business should go. That makes it a better first stop for comparison than an app tied to only one provider.
The broader car-care angle is another reason I would keep it in my toolkit. When I am evaluating whether to keep an older vehicle, the insurance payment is only one part of the decision. Seeing insurance alongside maintenance and repair considerations encourages a more realistic calculation. I might discover that a small premium reduction does not change the fact that the vehicle is becoming costly, or that keeping the car still makes sense if the repair outlook is manageable.
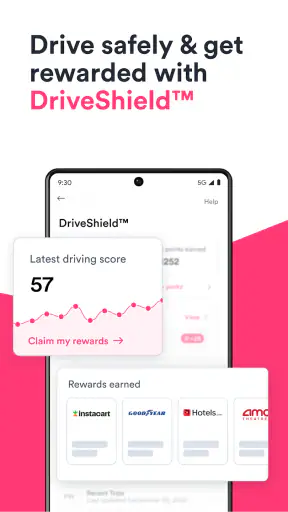
I also like the idea of using safe-driving discounts as a reason to pay attention to driving habits, rather than treating insurance as a completely fixed expense. The practical trade-off is that a discount linked to driving behavior may require me to accept a different kind of evaluation than a traditional policy. Anyone who values privacy or dislikes behavior-based programs should think carefully before choosing that route.
Jerry has enough public traction to feel like an established option rather than an obscure experiment. It has an average rating of 4.4 from around 17 thousand ratings, and it has passed the one-million-install mark. Those figures do not guarantee that every quote or support interaction will suit me, but they do suggest that many drivers have considered the same comparison problem.
A realistic everyday scenario
Imagine I receive a renewal notice while also hearing a grinding sound from my car. My first instinct might be to focus only on the insurance increase, but that would miss the larger issue. I could use Jerry to review insurance alternatives while separately estimating the likely repair and maintenance burden. If the car needs a costly repair soon, a slightly cheaper policy may not be enough to justify keeping it. If the repair is minor and the vehicle remains dependable, the comparison may help me reduce recurring costs without replacing the car.
That is where the app feels more useful than a simple insurer calculator. It gives me a prompt to consider the whole ownership picture. I still need a mechanic’s opinion for a mechanical problem and I still need to read insurance documents, but the app helps connect two decisions that are often made separately.
Safe-driving discounts require a personal trade-off
A safe-driving discount sounds appealing, but I would not judge it only by the possible saving. I would first ask whether the program fits my habits and expectations. A driver who wants feedback and is comfortable with driving being evaluated may find it motivating. Someone who frequently shares a car, drives unusual hours, or dislikes monitoring may prefer a conventional pricing approach.
I would also avoid changing my driving simply to chase a discount in ways that make me less safe. Smooth, attentive driving is worthwhile on its own. The discount should be a secondary benefit, not the main reason I make an unsafe or uncomfortable choice. This is an important distinction that is easy to miss when insurance comparisons focus heavily on price.
What the app does not replace
Jerry is not a substitute for reading the policy contract. I would still verify the insurer, coverage limits, deductibles, exclusions, claims process, and any conditions that matter to my situation. If I have a complicated driving history, multiple vehicles, unusual use of a car, or specific coverage needs, I may want to speak with an agent or contact an insurer directly.
It also does not replace a repair professional. A cost comparison can help me plan, but it cannot diagnose a warning light or tell me whether a noise is safe to ignore. For maintenance decisions, I would use the app as a budgeting aid and pair it with a trusted mechanic’s assessment. That combination is more reliable than treating an estimated ownership cost as a promise.
When a different option may fit better
I would choose a direct insurer app when I already know which company I want and my priority is policy management. In that situation, a comparison service may add an extra step. The insurer’s own app is likely to be the more natural place for documents, payments, claims, and account-specific questions.
An independent insurance agent may be a better fit when my situation is difficult to explain through a standard digital flow. A person can ask follow-up questions, identify gaps, and help me understand why one policy differs from another. That personal guidance can matter more than convenience for drivers with several vehicles, unusual coverage requirements, or a complicated claims background.
A dedicated maintenance or vehicle-record app may be preferable if insurance is not my concern. Jerry’s combined focus is useful for someone making a broader ownership decision, but a specialized tool can be more suitable when I mainly need service reminders, repair records, or a detailed log for one vehicle. I would not install Jerry expecting it to replace every automotive tool I use.
There is also a case for doing the comparison manually. Some drivers prefer collecting quotes from insurers one by one, asking questions directly, and keeping their own spreadsheet. That approach takes more effort, but it can provide a strong sense of control. Jerry is a convenience layer; it is not automatically superior for someone who enjoys researching every option independently.
The app’s age rating is Everyone, which makes it broadly approachable for ordinary drivers, but that does not mean every insurance decision is simple. Younger or inexperienced drivers may still need help understanding liability, deductibles, and the consequences of selecting less protection. A friendly interface should not be mistaken for a simplified contract.
Privacy, accuracy, and the cost of convenience
The main non-financial trade-off is information. To compare insurance and personalize the experience, I would expect to provide details about myself, my vehicle, and my driving situation. I would review the app’s current permissions and privacy explanations before proceeding, particularly if I am considering a safe-driving program. Convenience is valuable, but I want to understand what I am agreeing to and why certain information is needed.
Accuracy is equally important. I would not guess at annual mileage, vehicle use, previous incidents, or household-driver details just to move through a form faster. A quote based on incorrect information is not a real saving. Keeping my records open while completing the process is a small habit that can prevent a much larger problem later.
Switching insurance without creating a gap
The cost of switching is not limited to the new premium. There may be an administrative burden, a cancellation process, a different payment schedule, or a need to provide proof of the replacement policy. I would compare the total first-term cost and the coverage, then confirm the start date before ending the old policy.
I would also check whether automatic payments, roadside assistance, bundled products, or household arrangements are connected to the existing insurer. These details are easy to overlook when the comparison screen highlights only the main price. Jerry can help me find alternatives, but I remain responsible for making the transition cleanly.
For that reason, I would use the app in two stages. First, I would explore and shortlist. Second, I would verify the chosen policy directly and complete the switch only after the documents are clear. This workflow takes a little longer than accepting the first appealing result, but it reduces the risk of discovering a coverage problem after cancellation.
My recommendation for different kinds of drivers
I recommend Jerry to drivers who are approaching renewal, want to compare insurance options, and would benefit from considering maintenance and repair costs at the same time. It is especially appealing if I am trying to decide whether to keep an older car, reduce recurring expenses, or investigate whether safe-driving discounts suit my habits. The fact that it is free removes an obvious barrier to trying the comparison process.
I would be more cautious if I already have a highly customized policy, need detailed personal guidance, or strongly prefer to deal with one insurer directly. In those cases, an agent or direct provider may give me a clearer path. I would also skip the safe-driving angle if the required monitoring arrangement makes me uncomfortable; a discount is not worth accepting a program that conflicts with my privacy expectations.
The current version is 3.134.1, and the app requires an operating system version of 10 or later. That makes checking device compatibility part of the sensible setup process, especially if I am using an older phone. It is a small practical detail, but an insurance tool is most useful when it is available before a renewal deadline rather than discovered after the device cannot run it.
Jerry, Inc. has built an app that is more useful as a decision guide than as a complete replacement for insurers, agents, mechanics, or personal budgeting. I would use it to widen my view, compare realistic choices, and connect insurance with the cost of keeping a car on the road. My strongest advice is to use the app to compare carefully, not to choose blindly.
Overall, Jerry: Insurance & Car Care earns a place on my phone when I want to reassess ownership costs or prepare for a policy renewal. Its best quality is the way it brings insurance and car-care thinking together. Its main limitation is that the convenience can tempt me to focus on a headline result instead of the details that determine real value. Used patiently, it is a sensible free starting point; used as an automatic shortcut, it is less convincing.
For me, the final decision is straightforward: try it when I am actively comparing, keep my current policy details beside me, verify every coverage difference, and treat any safe-driving discount as optional rather than guaranteed savings. That approach lets the app do what it does well while leaving the important judgment where it belongs—with the driver.
FAQ
What is Jerry: Insurance & Car Care, and what can I use it for?
Jerry: Insurance & Car Care is a mobile platform designed to help drivers manage several vehicle-related tasks in one place. Depending on your location and eligibility, it can help you compare or purchase car insurance, review policy information, organize renewal details, and keep track of car-care needs. It is intended to simplify routine ownership tasks, although available services may vary by state, insurer, vehicle, and user profile.
Can Jerry help me find cheaper car insurance?
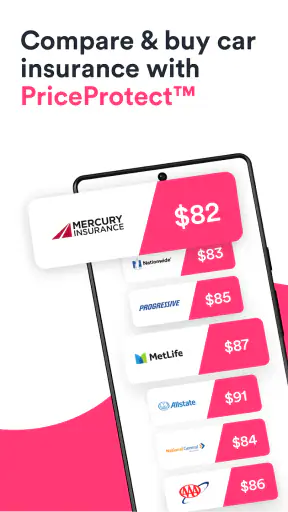
Jerry can compare insurance options from participating providers and present quotes based on the information you submit, such as your driving history, vehicle, address, coverage preferences, and personal details. However, the app cannot guarantee that every insurer or discount is included, and the lowest quote may not provide the coverage you need. Always review limits, deductibles, exclusions, fees, and final policy documents before switching.
Is Jerry an insurance company or an independent insurance broker?
Jerry is not generally the company that underwrites your insurance policy. It operates as a platform and insurance agency or broker in applicable markets, helping users obtain and manage offers from participating insurance carriers. Your actual coverage, claims decisions, premiums, and policy terms come from the selected insurer. Before purchasing, check the provider name, licensing information, payment terms, and cancellation conditions shown in the app.
Can I manage my existing car insurance policy through the app?
The app may allow eligible users to view policy-related information, receive reminders, manage renewal tasks, and get assistance with certain insurance services. The exact level of support depends on whether your policy was purchased through Jerry, the participating carrier, and your location. For claims, coverage disputes, roadside emergencies, or urgent policy changes, contacting the insurance company directly may still be necessary.
Does Jerry provide car maintenance and repair services too?
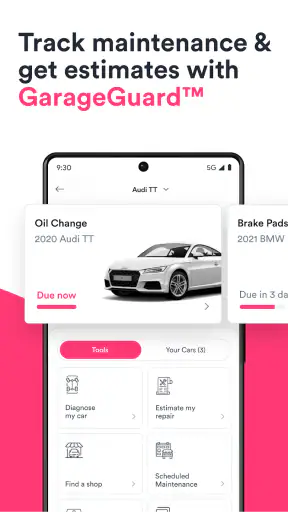
Jerry includes car-care features intended to help drivers stay organized with maintenance, vehicle information, service reminders, and selected repair or ownership resources. These tools can be useful for tracking routine responsibilities, but they do not replace a qualified mechanic’s inspection or professional advice. Service availability, pricing, repair partners, and maintenance recommendations may differ by region, vehicle model, and the information entered into the app.


